
If your staffing agency had 50+ full-time employees and full-time equivalents last year, the ACA likely applies to you. That means I need to know who the common-law employer is, who counts as full-time, when coverage must be offered, and what records must be kept.
Here’s the short version:
- Full-time under the ACA means 30 hours per week or 130 hours per month
- New full-time hires usually must get an offer by the first day of the fourth full calendar month
- Variable-hour and seasonal workers can often be tracked with the look-back method
- Breaks under 13 weeks usually do not reset ACA status
- Coverage must meet MEC, minimum value, and affordability rules
- In 2026, affordability is tied to 9.96%
- ALE penalties can reach $3,340 under 4980H(a) or $5,010 under 4980H(b)
What makes staffing harder is simple: workers move between assignments, hours shift, and rehires happen all year. So I can’t treat ACA tracking like basic payroll. I need one clear record for each worker that ties together hours, breaks in service, offer dates, enrollments, and reporting data.
This guide walks through the core ACA rules for staffing firms in plain English, so I can spot risk early and keep offers and reporting on time.
Streamline Your ACA Compliance – What Staffing Firms Need to Know in 2024
sbb-itb-aa28329
Step 1: Identify the ACA Employer and Full-Time Workers
Start with two basic questions: Who is the common-law employer? And who counts as full-time? Those two calls set the clock for measurement periods and tell you when coverage offers need to go out.
Common-Law Employer Rules in Staffing Arrangements
The ACA employer mandate applies only to the common-law employer. That means the party with the right to direct and control the worker’s services.
The IRS looks at the facts on the ground. It reviews who controls day-to-day work, who can hire, fire, or discipline the worker, who provides tools and equipment, and who sets pay rates and work rules. A contract matters, but it doesn’t settle the issue by itself. What matters most is how the arrangement works in practice.
In many temp placements, the staffing agency handles recruiting and hiring, sets HR rules, and can reassign the worker or end the assignment. In that setup, the agency is often the common-law employer. In other arrangements, the client may control work conditions and have the power to terminate workers directly. When that happens, the duty may shift to the client.
Map each client relationship to the IRS control factors. Then write down the result and make sure the service agreement matches the party handling ACA coverage and reporting.
Once you’ve assigned that duty, the next step is figuring out whether the worker reaches full-time status.
ACA Full-Time Status: 30 Hours Per Week or 130 Hours Per Month
ACA full-time status begins at 30 hours of service per week or 130 hours per month. That rule drives when the agency must offer coverage. Job title alone doesn’t decide it.
For workers placed in guaranteed 40-hour roles, the answer is plain from day one. For others – seasonal crews, short-project teams, or workers brought in for a shutdown or pipeline repair – hours may be hard to pin down at hire. In those cases, the IRS lets agencies treat them as variable-hour employees when full-time status can’t be determined at placement.
That said, this is one area where sloppy records can come back to bite you. Document why the worker was placed in the variable-hour bucket. Use past hours for similar roles, expected client schedules, and a written explanation showing why the hours were uncertain. If an agency labels an obviously full-time role as variable-hour just to delay a coverage offer, the IRS can challenge that in an audit.
Monthly Method vs. Look-Back Measurement Method
After workers are classified, you need a way to track whether they hit the full-time threshold. The ACA gives employers two options.
- Monthly method: treat a worker as full-time in any month with 130 hours of service. This works best for stable schedules.
- Look-back method: average hours over a 3- to 12-month measurement period, then treat the worker as full-time for the stability period.
For construction crews that surge during a project and slow down between jobs, the look-back method is usually much easier to manage. Many staffing firms in construction, energy, logistics, and healthcare use it for variable-hour and seasonal workers because it fits project-based demand better.
| Method | Best Use Case | Key Advantages | Operational Risks |
|---|---|---|---|
| Monthly measurement | Smaller agencies with stable, predictable full-time roles | Simple to administer; status tied directly to monthly hours | Volatile eligibility for fluctuating schedules; higher risk of missed timely offers |
| Look-back measurement | Agencies with variable-hour, seasonal, or project-based workforces | Stable eligibility during stability periods; fits cyclical demand patterns | More complex setup; requires disciplined tracking of measurement and stability periods |
Whichever method you choose, use it the same way across the group it applies to, and document the choice in writing.
Once that method is in place, Step 2 moves to initial, administrative, and stability periods – the timing rules that control when coverage offers must be made.
Step 2: Apply Measurement Periods and Make Offers on Time
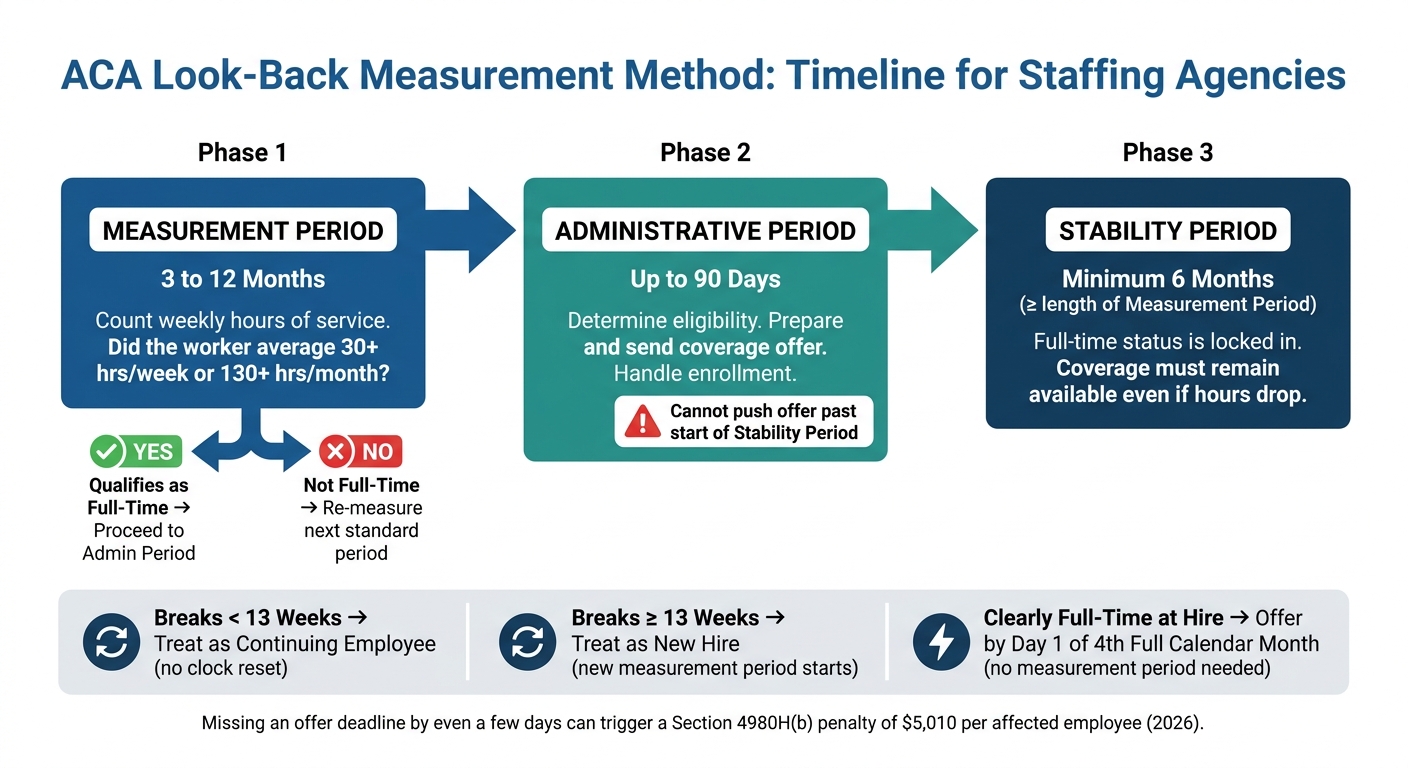
ACA Compliance Timeline for Staffing Agencies: Look-Back Method Explained
Once you pick a monthly or look-back method, the next job is simple in theory and easy to mess up in practice: track the measurement, administrative, and stability periods without missing the offer deadline.
That deadline comes from the measurement method you chose in Step 1. For staffing agencies, this means each worker’s hours, assignment dates, and breaks in service have to be treated as ACA data, not just payroll data.
Initial Measurement, Administrative, and Stability Periods Explained
Under the look-back method, three back-to-back periods determine when a coverage offer has to go out.
- Measurement period: This is the span when you count hours to see whether a worker averaged 30 or more hours per week. For new variable-hour employees, this is the initial measurement period. It can run from 3 to 12 months starting on the hire date or the first day of the next month. For existing employees, the standard measurement period follows a fixed calendar schedule set by the employer.
- Administrative period: This period can last up to 90 days after the measurement period ends. During this time, the agency figures out eligibility, handles enrollment, and sends coverage offers. The administrative period cannot delay the offer beyond the start of the stability period.
- Stability period: If a worker is found full-time based on the measurement period, the stability period locks in that status – and the coverage duty – for at least 6 months and for no less time than the measurement period itself. Even if the worker’s hours fall during the stability period, coverage still has to stay on the table.
These periods run in order. They also need to be set out in writing before they start. If an employer changes them mid-year or applies them unevenly across a worker group, that can create audit exposure.
When to Offer Coverage Based on Worker Type
Variable-hour workers move through the look-back timeline. Workers who are plainly full-time at hire don’t get that delay.
- New full-time employees – workers hired into a role with set hours of 30 or more per week – must get a coverage offer by the first day of the fourth full calendar month of employment, or earlier. There is no measurement period for workers who are clearly full-time on day one.
- Variable-hour and seasonal employees go through the initial measurement period before eligibility is decided. If they average 30 or more hours per week during that period, a coverage offer must be sent before the stability period starts, during the administrative window.
- Ongoing employees are measured during the standard measurement period. If they qualify, coverage must be offered for the entire stability period that follows, no matter how their hours move around during that time.
A deadline missed by even a few days can trigger a Section 4980H(b) penalty if the worker later gets a premium tax credit through the Marketplace. For agencies juggling dozens of rotating assignments, that risk adds up fast.
Breaks in Service and Short-Term Assignments
When a worker leaves and comes back, the gap in service has to be logged the right way so the ACA measurement record stays in place.
The IRS treats breaks in service in two buckets:
- Breaks of fewer than 13 consecutive weeks (26 weeks for educational institutions): If the worker returns inside that window, the agency must treat the person as a continuing employee, not a new hire. That means the earlier measurement history carries forward. And if the worker was in a stability period when they left, they may have to be offered coverage right away upon return.
- Breaks of 13 weeks or more: The worker may be treated as a new hire, and a new initial measurement period starts on the rehire date.
For project-based staffing, this matters a lot. A pipefitter might finish a refinery shutdown, leave, and come back three months later for a pipeline repair. If the break is under 13 weeks, the agency cannot reset the measurement clock. Treating that returning worker as a new hire just to delay a coverage offer is a recordkeeping mistake the IRS can spot in an audit.
Short-term assignments bring a similar problem. A worker who moves through several brief assignments with the same agency may stack enough hours across all of them to cross the full-time line during the measurement period. Hours have to be tracked across every assignment, not just the one the worker is on today.
Once those periods are tracked and the deadlines are met, the next issue is whether the coverage offer itself meets ACA standards.
Step 3: Meet Coverage Standards and Document the Offer
Hours and deadlines help you get to the offer. But ACA compliance comes down to two things: the plan itself and the records behind it.
Minimum Essential Coverage, Minimum Value, and Affordability
MEC means major medical coverage. MV means the plan pays at least 60% of allowed costs. Affordability means the employee’s share of the premium for the lowest-cost MV plan must stay within the 2026 limit of 9.96% of household income, which is usually tested with IRS safe harbors.
If an employer fails to offer MEC to at least 95% of full-time employees and their dependents, it can trigger the 4980H(a) penalty: $3,340 per full-time employee per year in 2026, minus the first 30 employees. If the offer is unaffordable or doesn’t meet MV, the 4980H(b) penalty can apply: $5,010 per affected employee who gets a premium tax credit in 2026.
Those are the first rules to check. After that, the next issue is simple: who has to make the offer when the client, not the agency, is the common-law employer.
How a Staffing Agency Can Offer Coverage When the Client Is the Common-Law Employer
When the client is the common-law employer, the client holds the ACA duty. Still, the IRS gives staffing firms a usable safe harbor. If the staffing agency offers ACA-compliant coverage through its own health plan, that offer is treated as the client’s offer if the client pays a higher fee for employees who enroll in coverage than for similar employees who do not.
That last part matters. A flat rate increase across all workers does not meet the rule. The fee difference has to be tied to actual enrollment.
| Factor | Staffing Agency Is Common-Law Employer | Client Is Common-Law Employer (Agency Safe Harbor) |
|---|---|---|
| Who must offer ACA coverage | Staffing agency | Client (satisfied via agency’s plan offer) |
| Which plan is used | Agency’s group health plan | Agency’s group health plan, administered on the client’s behalf |
| Fee structure | Standard markups; no enrollment-based differential required | Contract must show higher bill rate for enrolled workers vs. non-enrolled workers |
| Who bears ACA penalty exposure | Staffing agency | Client, though indemnity clauses may shift some risk for administrative failures |
| Reporting responsibility | Agency files Forms 1094-C/1095-C | Client files; agency provides enrollment and offer data |
In practice, the staffing contract should make this plain. It should spell out the fee difference, name the plan covering the workers, and set data-sharing terms so the agency can give the client the offer and enrollment records needed for reporting.
Records That Prove a Valid ACA Offer
Once the offer meets ACA rules, the next job is paperwork. And yes, this is the part people tend to treat like a chore. But in an audit, if it isn’t documented, it may as well not exist.
Keep a file for each full-time employee, including workers who said no to coverage. A clean file usually needs records in these three buckets:
- Employee dates and hours: hire, rehire, and termination dates, plus hours of service tied to each assignment and client site.
- Measurement and stability period files: determination dates, start and end dates for each period, and the written basis for variable-hour classification when it applies.
- Plan offer and enrollment proof: plan documents and the Summary of Benefits and Coverage (SBC) showing MEC and MV status; offer date and employee premium share; signed or electronic enrollment elections, declination forms, and dependent coverage notices; plus proof the employee got the materials, such as email logs, portal access records, or mailed notice tracking.
Project staffing gets messy fast when workers move from one assignment to the next. That’s why the records have to move with them. Hours, offers, and enrollments should all live in one worker file, not scattered across systems. Tools like ABLEMKR can build compliance tracking into workforce workflows and help produce complete ACA files for each worker.
Step 4: Handle Reporting, Audits, and Workforce Systems
Forms 1094-C and 1095-C for Staffing Agencies
Once you’ve documented coverage offers and worker files, use that same data for annual reporting.
Use the same worker records to prepare and review Forms 1094-C and 1095-C. When payroll, benefits, and HR data live in one place, it’s easier to cut down on silos and keep ACA tracking on track. Those same records also help when the IRS asks for audit support.
A Practical ACA Recordkeeping Schedule: Monthly, Quarterly, and Annual Tasks
ACA compliance gets a lot easier when you keep records on a rolling schedule instead of scrambling at year-end.
| Cadence | Task | Why It Matters |
|---|---|---|
| Monthly | Track worker hours and assignment visibility | Helps monitor full-time status across multiple sites |
| Monthly | Review new hires, rehires, and break-in-service dates | Keeps ACA measurement records accurate |
| Quarterly | Reconcile payroll, benefits, and timekeeping | Identifies discrepancies before annual reporting |
| Annual | Prepare Forms 1094-C and 1095-C; review codes | Finalizes reporting using one complete worker file |
These records also create the audit trail behind Forms 1094-C and 1095-C.
How Workforce Systems Support ACA Compliance in Project-Based Staffing
For project-based crews, one missed assignment update can throw off ACA reporting. Workers move between job sites, assignments start and stop, and hours may come from more than one source. Spreadsheets and scattered messages can create data gaps fast.
ABLEMKR centralizes worker hours, assignment history, and benefits records to support ACA reporting.
Keep hours, assignment history, benefits records, waivers, and form data aligned throughout the year.
FAQs
How do I know if my staffing agency is an ALE?
Under the Affordable Care Act, an Applicable Large Employer (ALE) is usually a company that averaged at least 50 full-time employees, including full-time equivalent employees, on business days during the previous calendar year.
If your staffing agency hits that 50-employee mark, it counts as an ALE. That means you need to follow the employer mandate rules, including offering affordable, minimum essential health coverage to full-time employees.
What counts as a break in service under the ACA?
The information provided does not cover ACA break-in-service rules.
It only deals with worker classification for tax and Department of Labor compliance. More specifically, it looks at:
- behavioral control
- financial control
- relationship type
So if you’re looking for ACA break-in-service guidance, this material doesn’t get into that topic.
What records should I keep to prove a valid ACA offer?
Keep clear, audit-ready records for at least four years to show that a valid ACA health insurance offer was made.
That file should include plan documents, contribution schedules, provider invoices, signed employment agreements, hours worked, pay stubs, fringe benefit valuations, and records showing contributions were deposited accurately and on time.
Put simply: if the IRS or Department of Labor comes knocking, messy records can turn a routine review into a headache. Organized files make it much easier to back up your compliance.


