
Misclassifying workers as independent contractors instead of employees can lead to serious financial and legal consequences. The IRS uses a three-factor test – behavioral control, financial control, and the nature of the relationship – to determine worker status. Misclassifications result in businesses owing unpaid taxes, penalties, and interest.
Key Takeaways:
- Unintentional Misclassification: Liable for partial unpaid taxes and fines (e.g., 1.5% of wages, 40% of FICA withholding).
- Intentional Misclassification: Severe penalties, including 20% of wages, 100% of FICA taxes, $1,000 fines per worker, and potential criminal charges.
- State Penalties: Some states, like California, impose additional fines of $5,000–$25,000 per violation.
- Prevention Tools: Use IRS Form SS-8 for classification guidance or programs like VCSP to resolve issues proactively.
Failing to classify workers correctly can cost businesses millions, as seen in cases from the construction and energy industries. Proper compliance tools and processes are essential to avoid these risks.
Master Employee vs Independent Contractor Classification Rules
sbb-itb-aa28329
IRS Guidelines for Classifying Workers
The IRS uses a three-factor test to determine whether a worker is classified as an employee or an independent contractor. This test builds on the concepts of control and misclassification, focusing on the substance of the working relationship rather than its formalities. According to the IRS, "Under common-law rules, anyone who performs services for you is your employee if you can control what will be done and how it will be done". Importantly, the business only needs the authority to exercise control – it doesn’t necessarily have to use it.
The three categories – behavioral control, financial control, and the type of relationship – work together to provide a complete understanding of the working arrangement. Let’s break them down, starting with behavioral control.
Behavioral Control
This category looks at whether the business directs or has the right to direct how tasks are performed. It includes:
- Instructions about when and where to work
- Guidance on what tools or equipment to use
- Requirements for the order or sequence of tasks
If the business provides extensive training on how to perform tasks, it points to an employee relationship. Independent contractors, by contrast, generally determine their own methods for completing work.
Financial Control
Financial control focuses on the worker’s economic independence and examines several factors:
- Investment in equipment or facilities: Independent contractors often provide their own tools or resources.
- Unreimbursed expenses: Contractors typically cover their own business expenses without reimbursement.
- Payment structure: Employees are usually paid a regular wage or salary, while contractors often receive a flat fee for completed projects.
- Opportunity for profit or loss: Contractors can earn more by working efficiently or lose money if their expenses exceed their income. Employees, on the other hand, receive steady pay regardless of the business’s profitability.
These financial elements help reveal whether the worker operates as an independent entity or is economically tied to the business.
Type of Relationship
This category examines the overall nature of the working relationship. Key factors include:
- Written contracts: While contracts can indicate the intended relationship, the IRS prioritizes actual working conditions over what’s written.
- Permanency of the arrangement: An indefinite, ongoing relationship suggests employee status, whereas project-based or time-limited work aligns with independent contractor status.
- Employee benefits: Offering benefits like health insurance, pension plans, or paid leave strongly indicates an employer-employee relationship.
Additionally, the IRS considers whether the worker’s services are a "key aspect" of the company’s regular operations. If the work is essential to the business’s core activities, it’s likely the company has the right to control those tasks, making the worker an employee.
Penalties for Misclassifying Workers
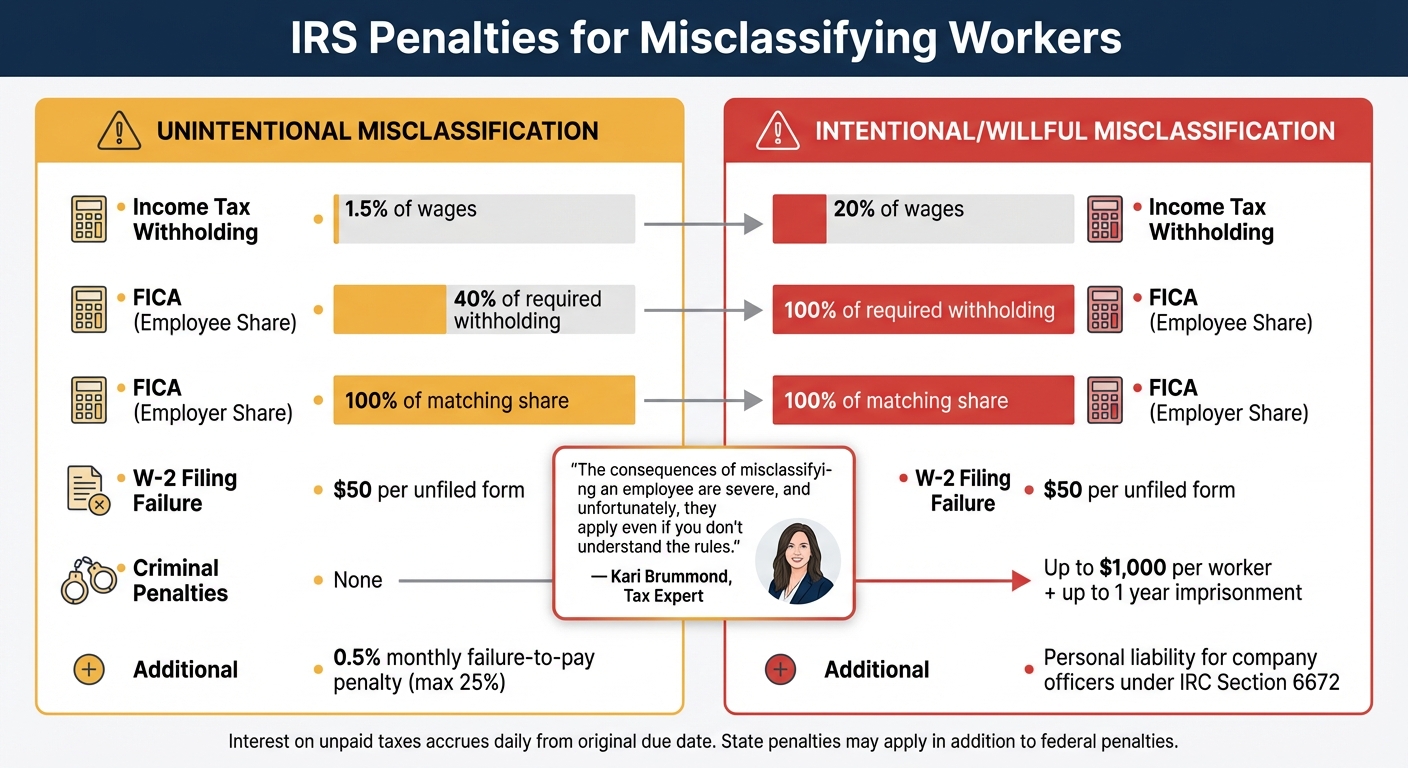
IRS Penalties for Worker Misclassification: Unintentional vs Intentional Violations
The financial impact of misclassifying workers often hinges on whether the IRS views the situation as an honest mistake or a deliberate attempt to evade taxes and benefits. This distinction can lead to vastly different outcomes, ranging from manageable fines to severe financial and even criminal penalties.
Penalties for Unintentional Misclassification
If a business unintentionally misclassifies an employee as an independent contractor, the IRS imposes penalties based on unpaid taxes. For income tax withholding, businesses are liable for 1.5% of the wages paid to the misclassified worker. On the FICA side, the employer must cover 40% of the employee’s required share and 100% of the employer’s matching share.
Additionally, there’s a $50 fine for every unfiled Form W-2. The IRS also applies a failure-to-pay penalty of 0.5% of the unpaid tax liability per month, up to a maximum of 25% of the total liability. Interest on unpaid taxes accrues daily from the original due date.
Penalties for Intentional Misclassification
When the IRS determines that misclassification was intentional or fraudulent, the penalties become far more severe. These include 20% of all wages paid and 100% of both the employee and employer shares of FICA taxes.
Criminal penalties also come into play for willful violations. Businesses can face fines of up to $1,000 per misclassified worker and up to one year of imprisonment. Under Section 6672 of the Internal Revenue Code, the IRS has the authority to personally penalize company officers responsible for failing to withhold taxes. Tax expert Kari Brummond emphasizes:
"The consequences of misclassifying an employee are severe, and unfortunately, they apply even if you don’t understand the rules. The penalties can be even worse if you willfully misclassify an employee".
This stark contrast in penalties highlights the importance of adhering to proper classification rules, with further nuances explored in state-specific regulations.
| Penalty Type | Unintentional Violation | Intentional/Willful Violation |
|---|---|---|
| Income Tax Withholding | 1.5% of wages | 20% of wages |
| FICA (Employee Share) | 40% of required withholding | 100% of required withholding |
| FICA (Employer Share) | 100% of matching share | 100% of matching share |
| W-2 Filing Failure | $50 per unfiled form | $50 per unfiled form |
| Criminal Penalties | None | Up to $1,000 per worker / 1 year prison |
State-Specific Penalties and Federal Comparisons
Federal penalties focus on unpaid employment taxes and violations of the Fair Labor Standards Act (FLSA), but state-level penalties often hit harder. States typically aim to replenish unemployment insurance funds and workers’ compensation premiums, which are drained when workers are misclassified. This dual enforcement approach means businesses can face both federal and state assessments at the same time. These state actions highlight the differences between federal and state measures.
Examples of State Penalties
Some states go beyond federal enforcement when it comes to misclassification. California, for instance, is one of the strictest states, with civil penalties ranging from $5,000 to $25,000 per violation. These fines are on top of federal penalties and any unpaid state unemployment insurance or workers’ compensation premiums. California also has the authority to issue stop-work orders or even bar businesses from obtaining government contracts.
Many states have agreements with the Department of Labor (DOL) to coordinate their enforcement efforts. If a state agency uncovers misclassification during an investigation – often while looking into unpaid unemployment taxes – it may alert the DOL, triggering a federal investigation into potential tax evasion. This collaboration has helped recover significant back wages for misclassified workers.
Federal vs. State Penalties: A Comparison
Federal penalties primarily address tax liabilities, while state penalties often include additional financial and labor-related recovery measures. The table below highlights the differences in focus and severity:
| Penalty Category | Federal (IRS/DOL/DHS) | State-Specific (e.g., California) |
|---|---|---|
| Tax Penalties | 3% of wages; 40%-100% of FICA taxes | Unpaid state taxes and premiums |
| Labor Standards | Back pay for overtime | Back pay for state minimum wages and paid leave |
| Civil Fines | $50 per unfiled W-2; $1,000 per I-9 violation | $5,000 to $25,000 per violation |
| Social Insurance | Social Security and Medicare (FICA) | Workers’ Compensation and Unemployment Insurance |
Federal enforcement leans heavily on recovering unpaid FICA taxes and income tax withholdings, while states impose steep civil fines for each violation. The Department of Labor usually limits its investigations to a three-year window for willful violations, but the Department of Homeland Security can extend its review to five years for I-9 compliance issues. This layered system of enforcement means businesses can face penalties from multiple agencies at once.
How to Prevent Misclassification with Compliance Tools
With the penalties for misclassification being so steep, taking proactive steps to ensure proper worker classification is non-negotiable. This is especially true in industries like construction and energy, where short-term or specialized projects often blur the line between employees and contractors. Thankfully, there are tools and programs designed to help businesses get it right from the start.
IRS Form SS-8 for Classification Determination
One effective way to determine worker classification is by using IRS Form SS-8. This form allows businesses to request an official determination directly from the IRS. It includes detailed questions about three key areas: behavioral control, financial control, and the nature of the relationship with the worker.
Before filing, it’s worth checking the IRS SS-8 Database for recent rulings in your industry. For instance, as of October 2025, the IRS frequently ruled that tradespersons, repair and maintenance workers, operators, and craftspersons in the "Construction, Trades & Technical Services" category should be classified as employees.
If you discover that workers have been misclassified, the Voluntary Classification Settlement Program (VCSP) offers a way to address the issue. By filing Form 8952, you can reclassify workers as employees for future periods while receiving partial relief from back taxes. This program is designed to help businesses correct misclassification issues proactively, avoiding the full brunt of penalties that could arise during an audit.
For companies looking for more comprehensive compliance solutions, platforms like ABLEMKR offer additional tools to safeguard classification efforts.
Using ABLEMKR for Compliance and Workforce Management
Industries like construction, energy, and extractives often juggle compliance challenges across multiple job sites. ABLEMKR simplifies this by embedding compliance tracking directly into workforce management processes. Its platform keeps detailed records of worker certifications, safety training, and classification status, ensuring compliance from the very beginning.
One of ABLEMKR’s standout features is its ability to provide W-2 workers with workers’ compensation coverage, which significantly reduces the risk of misclassification. The platform also integrates payroll workflows and offers real-time visibility into worker statuses, making documentation easily accessible if an audit occurs.
For industries where assembling crews quickly is critical – like emergency pipeline repairs or scheduled mine development – ABLEMKR’s compliance infrastructure minimizes both operational headaches and legal risks. This streamlined approach helps businesses stay focused on their projects without worrying about classification missteps.
Case Studies of Misclassification Penalties
Real-world examples highlight the steep financial and legal risks tied to employee misclassification.
Construction Industry: Massachusetts Case
In 2016, two construction companies in Massachusetts were found to have deliberately misclassified over 400 workers as independent contractors. Following an investigation by the U.S. Department of Labor, the companies faced fines totaling $2,360,000, covering back overtime wages and liquidated damages. One key factor driving the misclassification was the high cost of workers’ compensation premiums. In high-risk trades like roofing, these premiums can exceed 50% of payroll costs. While the companies may have aimed to cut costs in the short term, the long-term financial and legal repercussions far outweighed any temporary savings.
Energy Sector: Holland Services Settlement
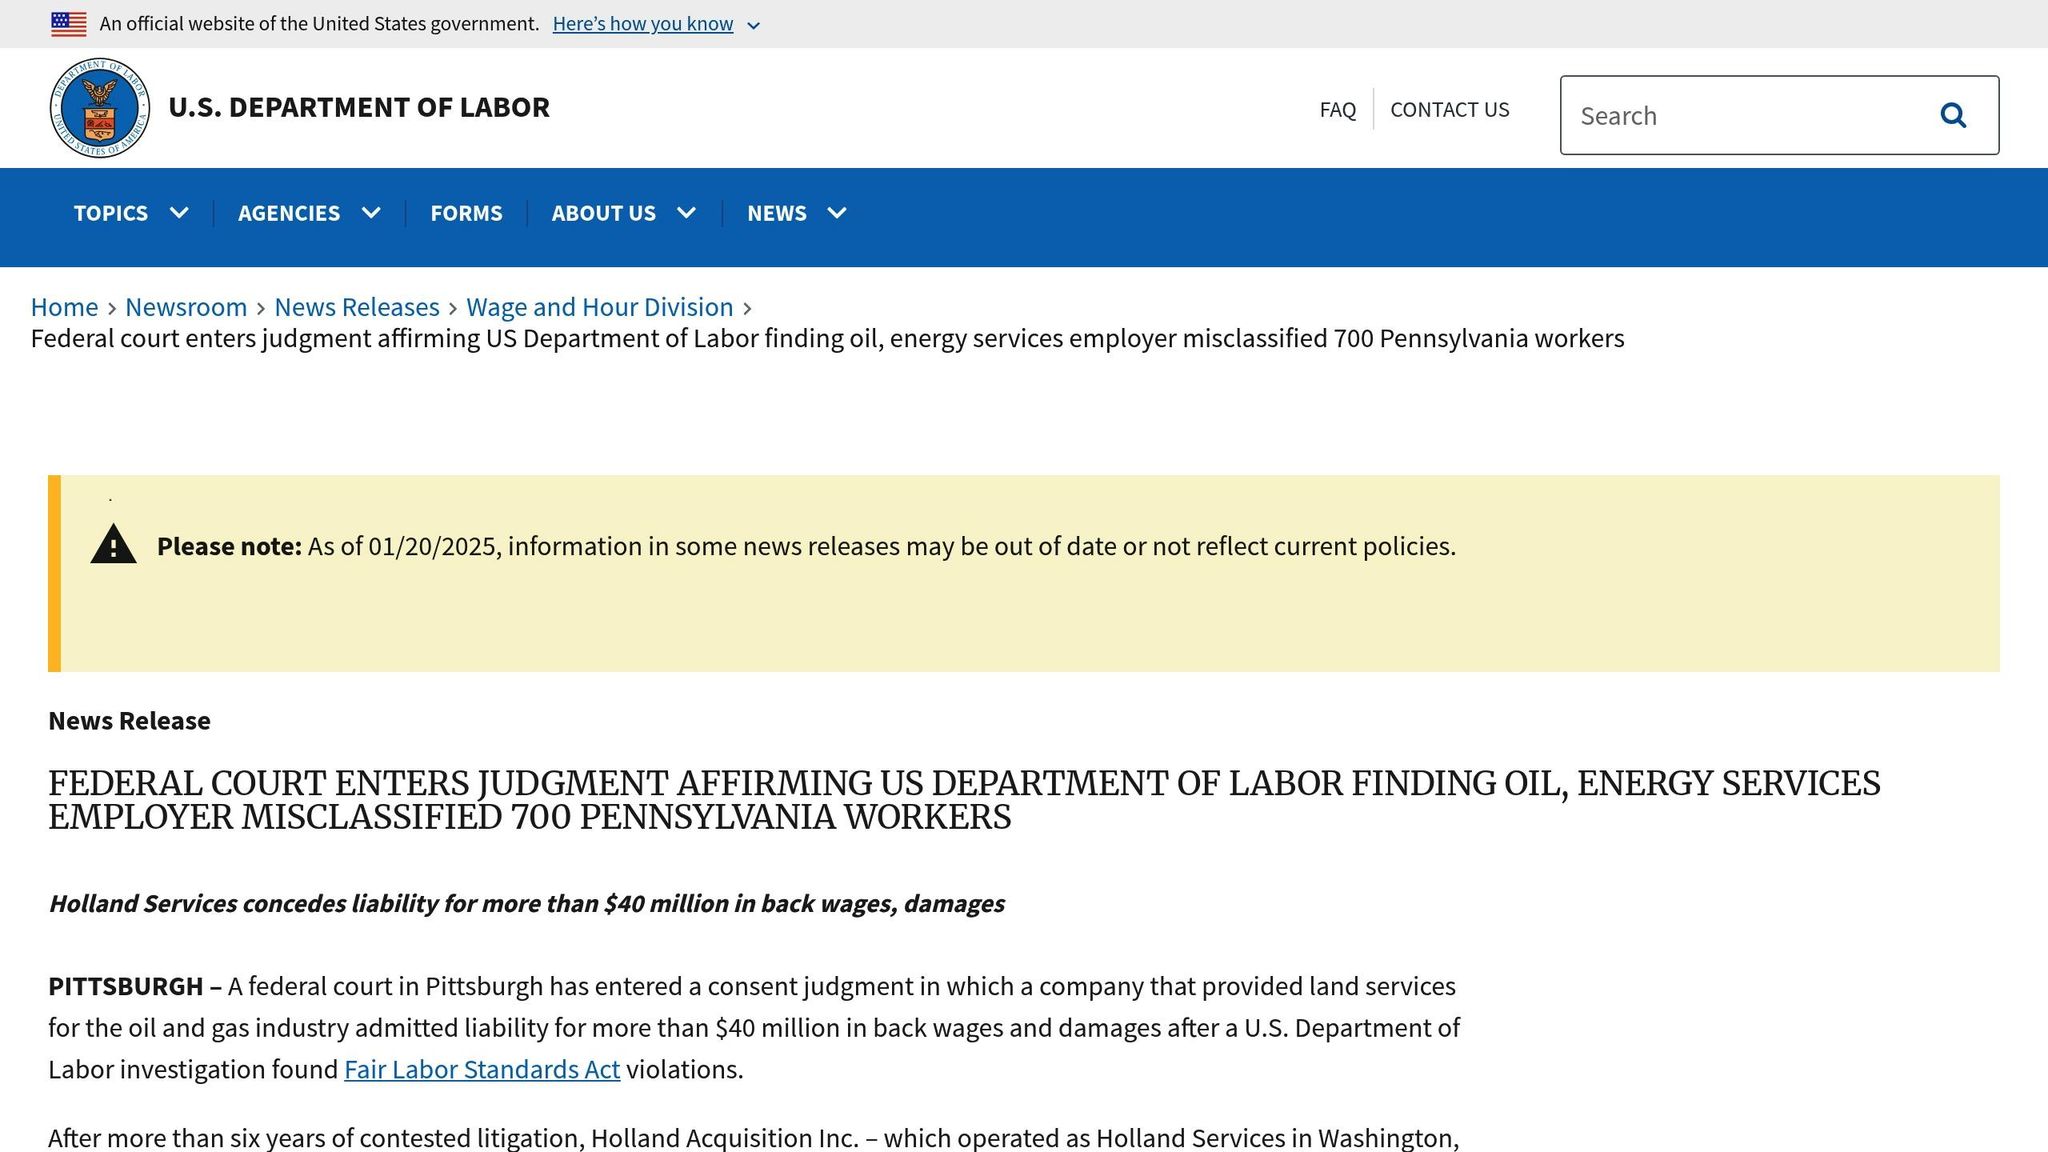
In 2021, Holland Services faced a similar issue, misclassifying 700 workers. The U.S. Department of Labor determined that the company owed $43,277,000 in back wages and damages. The energy sector often relies on project-based, on-demand work, but this alone does not justify classifying workers as independent contractors. The IRS evaluates factors like behavioral control, financial control, and the nature of the relationship to make such determinations. This settlement served as a costly reminder that misclassification can lead to severe penalties.
| Industry | Company/Case | Year | Penalty Amount | Workers Affected |
|---|---|---|---|---|
| Construction | Massachusetts Firms | 2016 | $2,360,000 | 400+ |
| Energy | Holland Services | 2021 | $43,277,000 | 700 |
These examples emphasize the importance of maintaining strict compliance measures. They also highlight the value of leveraging compliance tools to avoid such costly mistakes, as discussed earlier.
Conclusion
Worker misclassification carries serious financial consequences. The IRS bases its decisions on control factors, and any misclassification can lead to penalties for unpaid Social Security, Medicare, and income taxes. For willful misclassification, the IRS may impose penalties equal to 100% of the taxes that should have been withheld. Under Section 6672 of the Internal Revenue Code, company officers can even be held personally responsible for these amounts.
Examples from industries like construction and energy show just how quickly compliance failures can escalate into costly legal and financial repercussions. These cases emphasize the growing importance of compliance, especially as federal and state agencies collaborate more closely to address misclassification. While the Department of Labor can penalize violations going back three years, the Department of Homeland Security can enforce penalties for Form I-9 noncompliance over a five-year period. This underscores the need for businesses to act quickly and adopt better compliance practices.
Taking proactive steps is the best way to avoid these risks. Businesses should ensure reporting consistency by filing all required Form 1099s each year and maintain substantive consistency by treating similar workers the same way. For clarity on worker status, businesses can submit IRS Form SS-8, though this process may take over six months. Additionally, eligible employers might explore the Voluntary Classification Settlement Program (VCSP), which provides a way to reclassify workers with partial relief from federal employment taxes.
For industries like construction and energy – where project-based work increases the risk of misclassification – the stakes are even higher. Eric Gros-Dubois, Founding Partner at EPGD Business Law, warns:
"Companies that improperly classify their workers face substantial federal and state penalties, including class action litigation".
Modern workforce management tools can help businesses navigate these challenges. Platforms like ABLEMKR integrate compliance tracking into hiring and payroll processes, ensuring worker classification aligns with IRS and Department of Labor standards from the start.
The financial and legal risks outlined in this article make one thing clear: the penalties for misclassification far outweigh any temporary tax savings. Investing in accurate worker classification and reliable compliance tools not only protects your company’s bottom line but also shields you – and your leadership team – from personal liability.
FAQs
What evidence does the IRS look for during a worker-classification audit?
The IRS evaluates three main areas when determining worker classification: behavioral control, financial control, and the relationship between the parties.
- Behavioral control: This involves whether the employer dictates how tasks should be performed.
- Financial control: This looks at how the worker is paid and whether they have the opportunity for profit or loss.
- Relationship factors: These include written agreements, benefits provided, and the overall nature of the working relationship.
These elements collectively help decide if someone should be classified as an employee or an independent contractor.
How far back can the IRS and states assess taxes and penalties for misclassification?
The IRS and state tax authorities usually have up to three years to assess taxes and penalties for worker misclassification, as outlined in IRC § 6511. This three-year period typically applies to filing claims, but the exact timeframe can depend on the specific details of the case and the jurisdiction involved.
Can the VCSP reduce penalties if I reclassify workers now?
The Voluntary Classification Settlement Program (VCSP) offers a way to reduce penalties if you decide to reclassify workers as employees now. It provides limited federal employment tax liability for past cases where workers were treated as independent contractors, along with relief from penalties.
To participate, you’ll need to meet specific eligibility criteria and follow the outlined application process. This program can be a practical solution to address worker misclassification issues while keeping the financial burden lower.


